The hawkish hold is the regime. The FOMC held its target range at 3.50-3.75% on a 9-3 vote with three dissents, while the 10Y closed at 4.66%, just 9bp below its 4.75% 52w high.
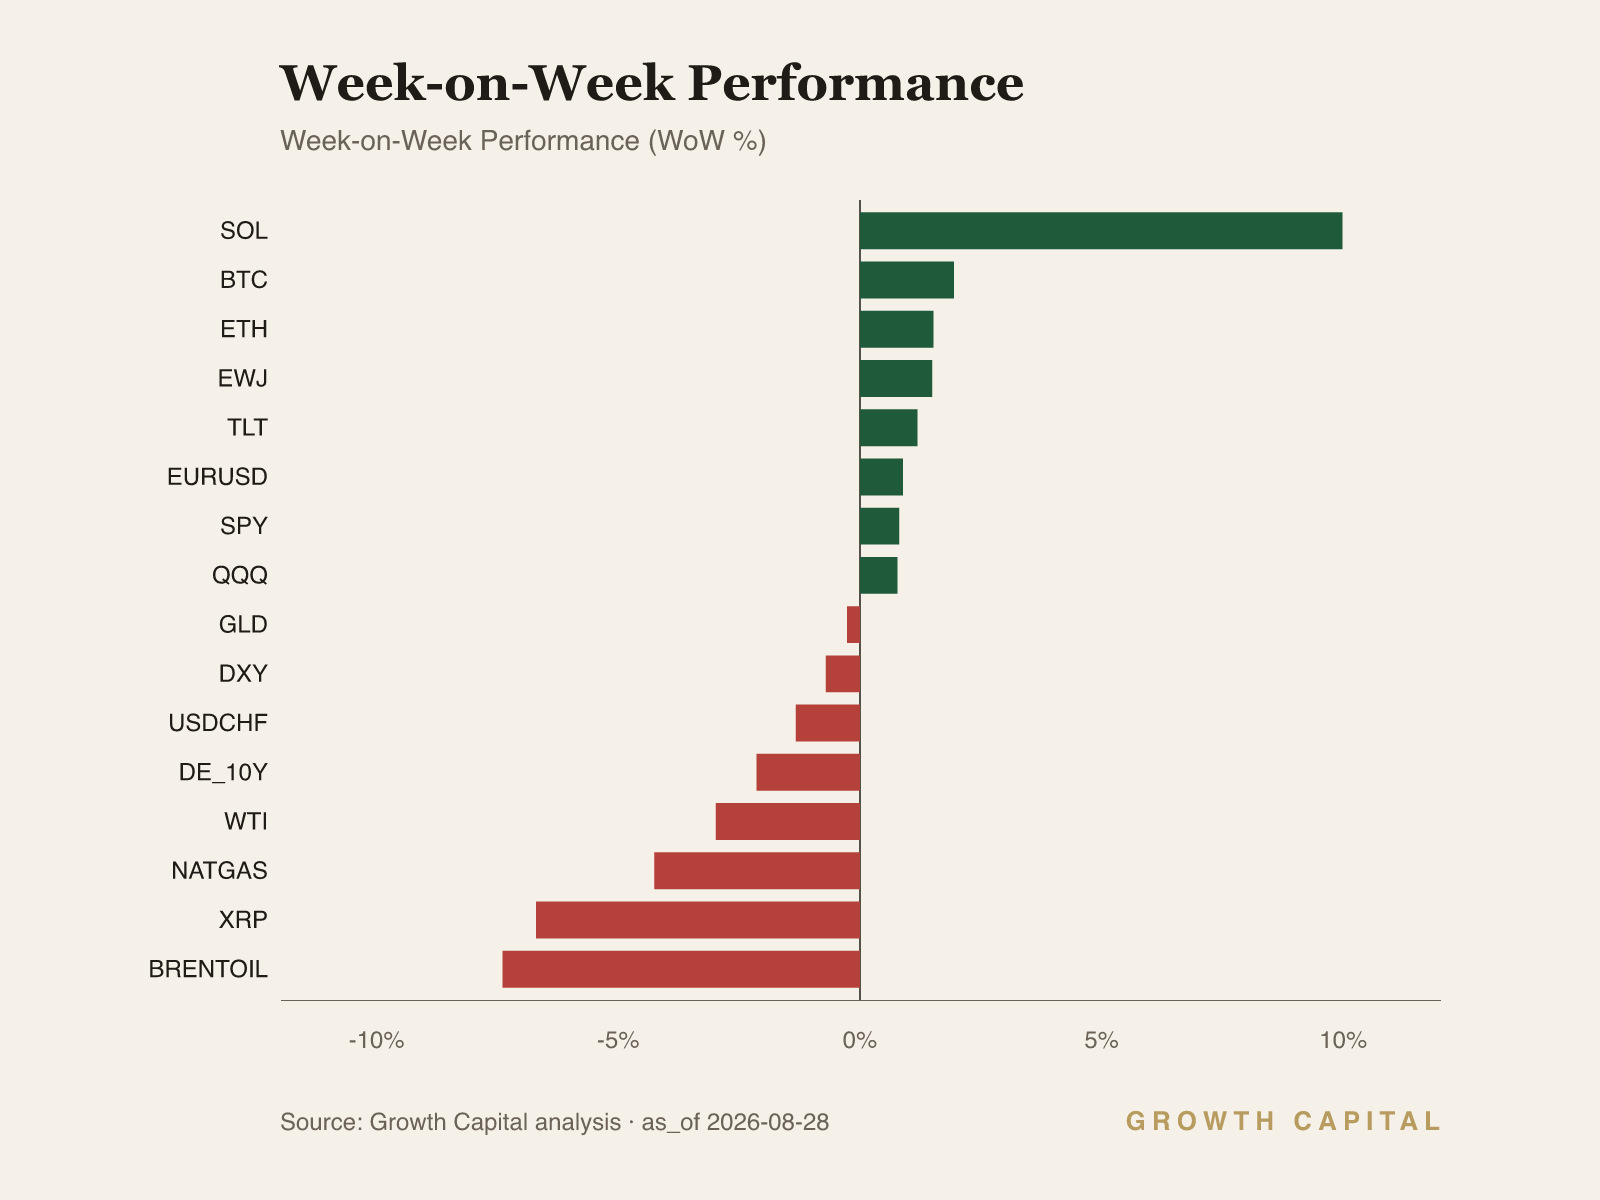
The crude correction is a reprieve, not a turn. Brent fell -7.4% WoW to $88.24/bbl on our primary feed, a print 0.8% above our crosscheck source, yet the +42.4% YTD supply premium is intact.
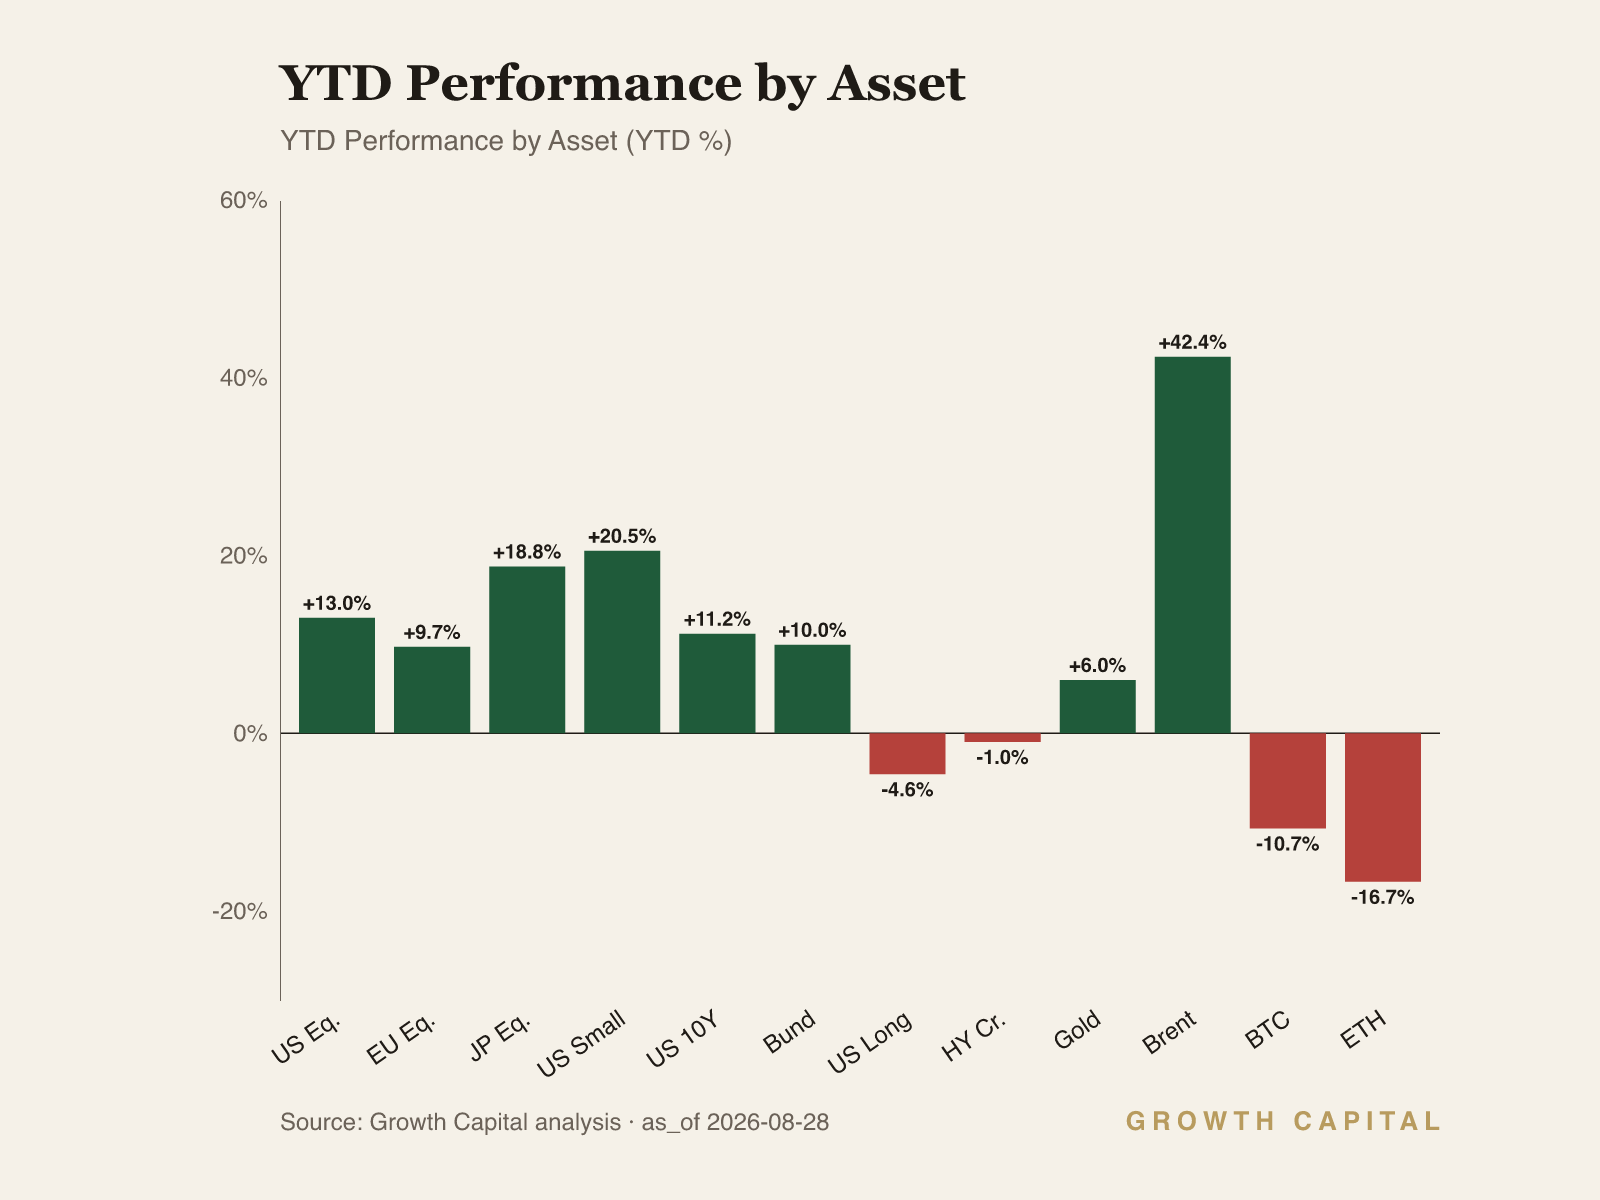
Risk assets are paying for a discount-rate peak that has not arrived. SPY sits +13.0% YTD within 0.8% of its $777.88 52w high while LQD is -3.2% YTD; the equity and credit tapes cannot both be right about rates.
Our positioning: An energy reprieve is not disinflation; we stay underweight duration until the 10Y decisively rejects its 4.75% high.
A hawkish hold meets an energy reprieve, and the long end declines to ratify either
Our regime read this week is a hawkish hold with an energy reprieve. The FOMC left its target range at 3.50-3.75% on a 9-3 vote, with three dissents, and framed inflation as elevated on supply shocks rather than excess demand. That framing is the load-bearing fact of the week: a central bank fighting a supply shock defers cuts even as growth cools, because de-anchored expectations cost more than foregone output. The bond market heard it, with the 10Y closing at 4.66%, 9bp from its 4.75% 52w high. Equities did not, with SPY at $771.95, +13.0% YTD, within 0.8% of its $777.88 52w high. The week's energy correction bought risk assets room but bought duration nothing, and that asymmetry is the information. Equities are pricing the reprieve; the long end is pricing the regime. We side with the long end.
The primary chain runs through the long end. The 10Y closed at 4.66%, +0.2% WoW and +11.2% YTD, 9bp below the 4.75% 52w high, while the 2Y held flat at 4.19%, leaving a 47bp positive gap between the 10Y at 4.66% and the 2Y at 4.19%. TLT moved against the grain with a +1.2% WoW bounce to $83.03, yet it remains -4.6% YTD and only 2.1% above its $81.35 52w low, and LQD at -3.2% YTD shows the same bleed inside IG credit. The transmission channel is energy prices to headline inflation expectations to term premium to long-end yields, and it is running with the policy rate switched off. With the funds target parked at 3.50-3.75% and the 2Y unchanged on the week, this year's repricing has been carried by maturity risk rather than policy-path risk: the 2Y is +20.7% YTD in yield terms against +11.2% for the 10Y, yet the market still demands a positive slope because it will not pre-pay for cuts while supply-driven inflation persists. The last link feeds equities, since a long end pinned near 4.66% caps the multiple and forces index returns to be earned in nominal cash flows. We are UW duration on a three-to-six-month horizon, accepting foregone 4.66% carry and the risk that the energy correction matures into demand-side disinflation. The asymmetry supports the stance: 9bp of room to the 4.75% high against a long repricing lower if the supply premium unwinds slowly. A weekly 10Y close below 4.19%, the level at which the gap to the 2Y closes to zero, would invert the call. That print would tell us the market has reclassified the energy shock as demand destruction, and duration would flip from threat to hedge.
Cross-asset, equities confirm the nominal-growth half of our regime read while credit confirms the rate half; the two tapes only look contradictory. SPY rose +0.8% WoW to $771.95, +13.0% YTD, QQQ added +0.8% WoW for +17.3% YTD, and EWJ led at +1.5% WoW, +18.8% YTD; against that, LQD is -3.2% YTD, HYG -1.0% YTD and EMB -1.2% YTD, three negative fixed income prints in a double-digit equity year. The reconciliation runs through the nominal-growth channel: equities are claims on nominal cash flows, so a supply-shock regime that lifts revenue lines can carry the index while the same regime marks down every fixed coupon. QQQ's +17.3% YTD against a 10Y that has risen +11.2% YTD in yield terms means the advance was earned in earnings and AI capex conviction rather than bought with multiple expansion. The stress point is high yield, where HYG at $79.89 sits within 1.5% of its $78.72 52w low and offers no cushion if nominal growth disappoints. We hold US equities at Neutral with an OW tilt to Japan through EWJ. The trade-off we accept is exporter concentration and yen-reversal risk against a 158.91 USD/JPY tape that keeps margins supported. An HYG break below $78.72 would cut our equity exposure regardless of index momentum, because it would mean the marginal borrower is being repriced. LQD returning to positive YTD territory would do the opposite and unlock a US upgrade.
The dollar is the second rail worth pricing. DXY fell -0.7% WoW to 118.06, -1.3% YTD, slightly oversold and 0.5% above its 117.44 52w low, while EURUSD rose +0.9% to 1.1684 into slightly overbought territory and GBPUSD added +0.6% to 1.3644. The rate structure does not justify the move: the ECB holds its deposit rate at 2.25% against a 3.50-3.75% funds target, and the German 10Y fell -2.1% WoW to 3.2% while the US 10Y rose, so the transatlantic gap widened in the dollar's favor. We read the softness as position-squaring ahead of Chair Warsh's Jackson Hole debut, not policy divergence. The franc complicates the risk-on read: USDCHF fell -1.3% WoW to 0.8008, a hedging bid underneath an otherwise constructive tape, consistent with credit's refusal to confirm equities. We hold EURUSD at Neutral and would fade strength at 1.1684. A weekly DXY close below 117.44 would force a rethink of the dollar-anchored framework.
Our falsifiers are explicit. Downside: a 10Y close above the 4.75% 52w high combined with HYG below its $78.72 52w low would confirm the shift from hawkish hold to stagflationary tightening, and we would cut equity beta, deepen the duration underweight and add to GLD at $422.22. Upside: a weekly 10Y close below 4.19%, the current 2Y level, would signal the market re-reading the energy shock as demand destruction, and we would add duration through TLT and lift US equities toward OW. Between those markers the regime call stands and patience is the position. A DXY break of 117.44 or SPY clearing $777.88 with credit confirmation would justify tactical adjustment without changing the thesis. We would rather re-underwrite the view a week late than front-run a regime shift the bond market has not validated.
Source: GrowthCapital analysis; market data per GC snapshot of 28 Aug 2026; FOMC and ECB communications; Nansen and Hyperliquid cohort data as cited.
Fixed Income
The long end declines to ratify the week's energy relief. The 10Y closed at 4.66%, +0.2% WoW and +11.2% YTD, 9bp from its 4.75% 52w high; the 2Y held at 4.19%, flat on the week and +20.7% YTD, and the 10Y at 4.66% against the 2Y at 4.19% keeps a 47bp positive slope. TLT bounced +1.2% WoW to $83.03 but sits -4.6% YTD, just 2.1% above its $81.35 52w low; credit confirms the bleed, with LQD -3.2% YTD and HYG -1.0% YTD. The mechanism is term premium, not policy path: with the funds target held at 3.50-3.75% on a 9-3 vote, the short end has nothing to reprice, so long-end movement is compensation for inflation uncertainty and duration supply. Reports of stepped-up Treasury buyback operations at the long end are a real counterweight, but an official bid that caps yields without changing the inflation process compresses term premium artificially and defers the repricing rather than cancelling it. The Bund adds information: the German 10Y fell -2.1% WoW to 3.2% while the US 10Y rose, so the transatlantic gap widened in the dollar's favor even as DXY softened -0.7% WoW, which tells us the week's dollar move is positioning, not rates. We stay UW duration via TLT and hold the front end at Neutral, collecting 4.19% with minimal maturity risk. A weekly 10Y close below 4.19% flips us to adding duration; a close above 4.75% extends the underweight and takes equity beta down with it.
Equities
The index tape confirms nominal growth, not a falling discount rate. SPY added +0.8% WoW to $771.95, +13.0% YTD and within 0.8% of its $777.88 52w high; QQQ rose +0.8% WoW for +17.3% YTD on an AI-led semiconductor bid after a strong Nvidia outlook; EWJ led developed markets at +1.5% WoW, +18.8% YTD. The mechanism matters more than the levels. With the 10Y at 4.66% and up +11.2% YTD in yield terms, multiple expansion is unavailable, so QQQ's +17.3% YTD has been earned in earnings and AI capex conviction, a narrower and more fragile source of return than a broad discount-rate decline would provide. That concentration cuts both ways: the same capex cycle that carried the index can mark it down on a single guidance miss, and the pre-Jackson-Hole caution across Asian sessions shows how little conviction sits behind the last 0.8% of upside. Japan is the cleaner expression: EWJ's +18.8% YTD comes with USD/JPY at 158.91, a level that keeps exporter margins wide without requiring any US multiple support. We hold US equities at Neutral and Japan at OW on a three-month horizon, accepting single-market concentration and yen-reversal risk as the cost of the cleaner earnings channel. A SPY close above $777.88 with IG credit back to positive YTD would upgrade the US view; an HYG break below its $78.72 52w low would cut the entire equity complex regardless of index momentum.
Commodities
Crude gave back a slice of its supply premium without surrendering the regime. Brent fell -7.4% WoW to $88.24/bbl on our primary feed, a print 0.8% above our crosscheck source, so we hold the exact level loosely while the +42.4% YTD gain stands. WTI declined -3.0% WoW to $83.90/bbl, also carrying a primary-versus-crosscheck gap of 1.5%, and retains a +46.7% YTD advance despite a down trend reading. The week's decline was driven by diplomatic option value: a stalemate in US-Iran talks removed near-term escalation premium while flows through the Strait of Hormuz continued, and profit-taking did the rest. The level, not the direction, is what matters for the macro chain, because crude at these prices keeps the energy pass-through into headline inflation alive, and that is why the long end would not rally on a single -7.4% week; the term-premium channel needs a sustained retreat, not a correction. Gold is the quiet confirmation of a hedged market: GLD eased -0.3% WoW to $422.22 yet holds +6.0% YTD, well below its $495.90 52w high, consistent with a bid for policy-credibility insurance without panic. We hold crude at Neutral, unwilling to short a +42.4% YTD supply regime or to chase it after a -7.4% week, and we keep GLD at OW as the cheapest two-sided hedge in the book. If weekly crude declines extend while the 10Y holds above 4.66%, the bond market is telling us it doubts the reprieve; a 10Y close below 4.19% is the cleaner trigger for the complex.
Digital Assets
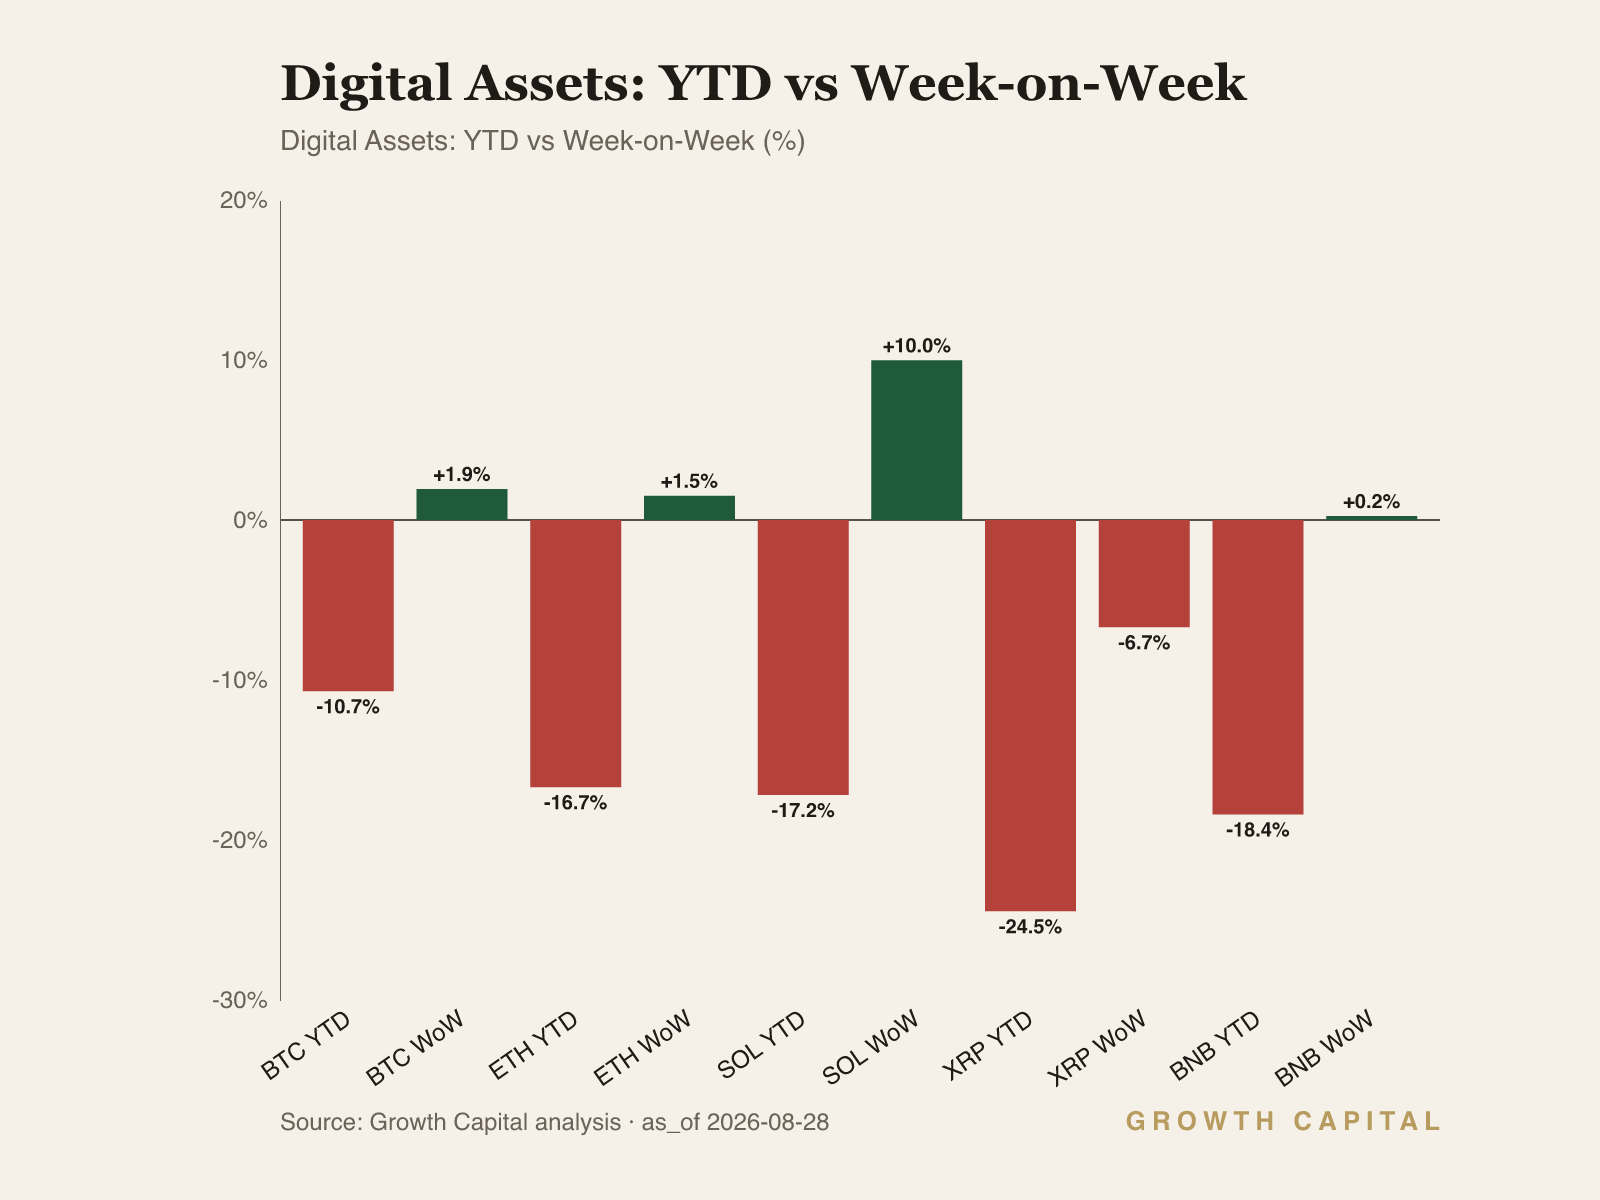
Crypto is a bifurcated tape under a rising-rate risk budget. BTC rose +1.9% WoW to $79,296.9 but remains -10.7% YTD and slightly overbought on our gauge, with dominance at 56.98% of a $2.79T total market cap and $474B of 24h turnover. ETH added +1.5% WoW to $2,502.25, still -16.7% YTD; SOL was the outlier at +10.0% WoW to $105.05, though -17.2% YTD. The mechanism: with the 10Y at 4.66% and the funds rate held at 3.50-3.75%, long-duration risk assets get no discount-rate support, so performance is being decided by cohort flows rather than macro liquidity. Those flows disagree by asset. BTC saw $18M of net exchange inflows at 1.6x the weekly average, a mild sell-side signal, while the Hyperliquid whale book runs net long $96.7M against a smart-trader net short of $11.1M; big money is long the dip, the sharper cohort is hedged. ETH shows the opposite and cleaner pattern: $203.2M of net exchange outflows at 1.4x average with smart traders accumulating $4.5M on-chain and running $26.2M net long in perps, the single best accumulation signal across the majors. SOL's +10.0% WoW arrives without complete cohort confirmation in this week's window, so we treat it as momentum rather than conviction. We are Neutral BTC, small OW ETH on the flow divergence, and Neutral SOL. ETH exchange flows flipping to net inflows cancels the overweight; BTC reclaiming positive YTD territory alongside net exchange outflows upgrades the complex.
GC Views
| Asset | View | Rationale |
|---|---|---|
| US_10Y | UW | UW duration: 4.66% is 9bp from the 4.75% 52w high with supply-driven inflation unbroken; no margin of safety. |
| US_2Y | N | Flat at 4.19% against a 3.50-3.75% hold; fair carry, no near-term repricing catalyst either way. |
| TLT | UW | The +1.2% WoW bounce fights a -4.6% YTD trend; we fade long-end rallies until a weekly 10Y close below 4.19%. |
| DE_10Y | N | -2.1% WoW to 3.2% widens the transatlantic gap; a hold-regime trade, not a trend we chase. |
| LQD | UW | -3.2% YTD with term premium still building; IG duration bleeds until the 10Y rejects 4.75%. |
| SPY | N | +13.0% YTD near the $777.88 high while credit is negative YTD; no multiple support with the 10Y at 4.66%. |
| QQQ | N | +17.3% YTD earned in AI earnings, not multiple; concentration risk rises while the 10Y holds 4.66%. |
| EWJ | OW | +1.5% WoW and +18.8% YTD with USD/JPY at 158.91 supporting exporter margins; our preferred DM equity tilt. |
| BRENTOIL | N | -7.4% WoW to $88.24 (primary prints 0.8% above crosscheck); the +42.4% YTD supply premium bars a short. |
| GLD | OW | +6.0% YTD at $422.22, well below the $495.90 high; the cheapest two-sided hedge against a credibility break. |
| BTC | N | +1.9% WoW to $79,297 but -10.7% YTD; $18M exchange inflows and a smart-trader short argue against chasing. |
| ETH | OW | $203.2M exchange outflows plus $4.5M smart-trader accumulation against a -16.7% YTD tape; small overweight. |
| EURUSD | N | +0.9% WoW to 1.1684, slightly overbought; dollar softness is positioning ahead of Warsh, not policy divergence. |
On-Chain Pulse
Cohort positioning across the majors splits along one fault line this week: on Hyperliquid, whales are net long BTC while smart traders lean short, and the books invert on ETH, where smart traders are long and whales carry the hedge. On-chain, the profitable cohorts are distributing into depressed prices across the set, with BTC near $79,297 and ETH near $2,502. We read the aggregate as a hedged, two-sided market with no directional consensus, which keeps position sizing small.
Bitcoin's book is big money long, smart money skeptical. On Hyperliquid, whales run net long $96.7M on a $2.2B gross open book, a net tilt of roughly 4% of gross exposure, and public figures add a further $56.8M of net length; smart traders sit on the other side, net short $11.1M, so the whale long outweighs the smart-trader short by nearly nine times in absolute size, but the sharper cohort is fading the level. On-chain, smart traders are effectively flat with a $91k net inflow, no conviction either way. The spot signal leans sell-side: exchanges took $18M of net inflows at 1.6x the weekly average, and the Funds and Top PnL cohort distributed $16.9M across 107 wallets at 1.1x average; profitable wallets are lightening into the +1.9% WoW bounce. That is a spot-versus-perps divergence in the uncomfortable direction, with derivatives length building while spot supply migrates toward exchanges. Our positioning implication is Neutral: at $79,296.9 and -10.7% YTD we will not short a whale-supported book, and we will not chase a bounce the smart-trader cohort is hedging while the exchange-flow tape quietly sells. A reversal to net exchange outflows is the print that would move us.
Ethereum carries the cleanest accumulation signal in the set, with the whale book as the dissent. Smart traders bought $4.5M net on-chain at 2.0x their weekly average across 567 wallets and run net long $26.2M on Hyperliquid perps, with public figures adding $75.6M of net length. Whales take the other side, net short $33.1M on a $1.5B gross open book, a hedge of roughly 2% of gross exposure that exceeds the smart-trader long by about 1.3x in absolute size. Distribution pressure is real: the Top PnL cohort sold $87.3M net at 2.4x average across 295 wallets, the largest single distribution print across all five majors this week. Against that, the exchange-flow signal is decisively constructive: $203.2M of net outflows at 1.4x average, coins that left venues even with the price -16.7% YTD at $2,502.25, supply moving away from the sell button while smart-cohort perp length builds. Our positioning implication is a small overweight: we side with smart-trader accumulation and the outflow tape against the whale hedge, sized for the possibility that the whales are right. A flip to sustained net exchange inflows, or the smart-trader perp book turning short, cancels the call.
This week's intel window carries incomplete cohort data for SOL, XRP and BNB, so we withhold per-asset reads rather than extrapolate from partial prints. SOL's +10.0% WoW spot move therefore stands unconfirmed by flow and we hold it at Neutral; the same discipline applies to XRP at -6.7% WoW and BNB at +0.2% WoW.
What We're Watching
Four markers govern the view. First, the 10Y: a weekly close above the 4.75% 52w high extends our duration underweight and cuts equity beta; a close below 4.19%, the current 2Y level, flips us to adding duration via TLT. Second, high yield: HYG below its $78.72 52w low forces an equity de-risking regardless of index momentum. Third, the dollar: a DXY close below the 117.44 52w low would signal a regime turn our framework does not currently price. Fourth, ETH exchange flows: a flip from the week's $203.2M net outflow to sustained inflows cancels our small overweight. Each threshold is a level, not a mood; we act on prints, and the CIO review hardens or rejects each call before it becomes policy.
This Week in Charts