Tightening has resumed and the bond market believes it. The FOMC's 25bp hike took the US 10Y to 5.01% and the 2Y to 4.74%, both 52-week highs.
Equity resilience is narrower than the index shows. QQQ gained +0.5% WoW while DIA fell -1.9% and IWM -1.7%, and credit sits oversold with LQD -4.9% YTD.
Crypto absorbed a hawkish week and a legislative setback. BTC rose +2.1% WoW to $78,382 with dominance at 55.94%, though long-heavy perp positioning still lacks spot sponsorship.
Our positioning: Global tightening has resumed into sticky inflation; we hold underweight long duration and reduced equity beta until the 10Y closes below 4.75%.
Global tightening resumes and the 5.01% ten-year is the fault line
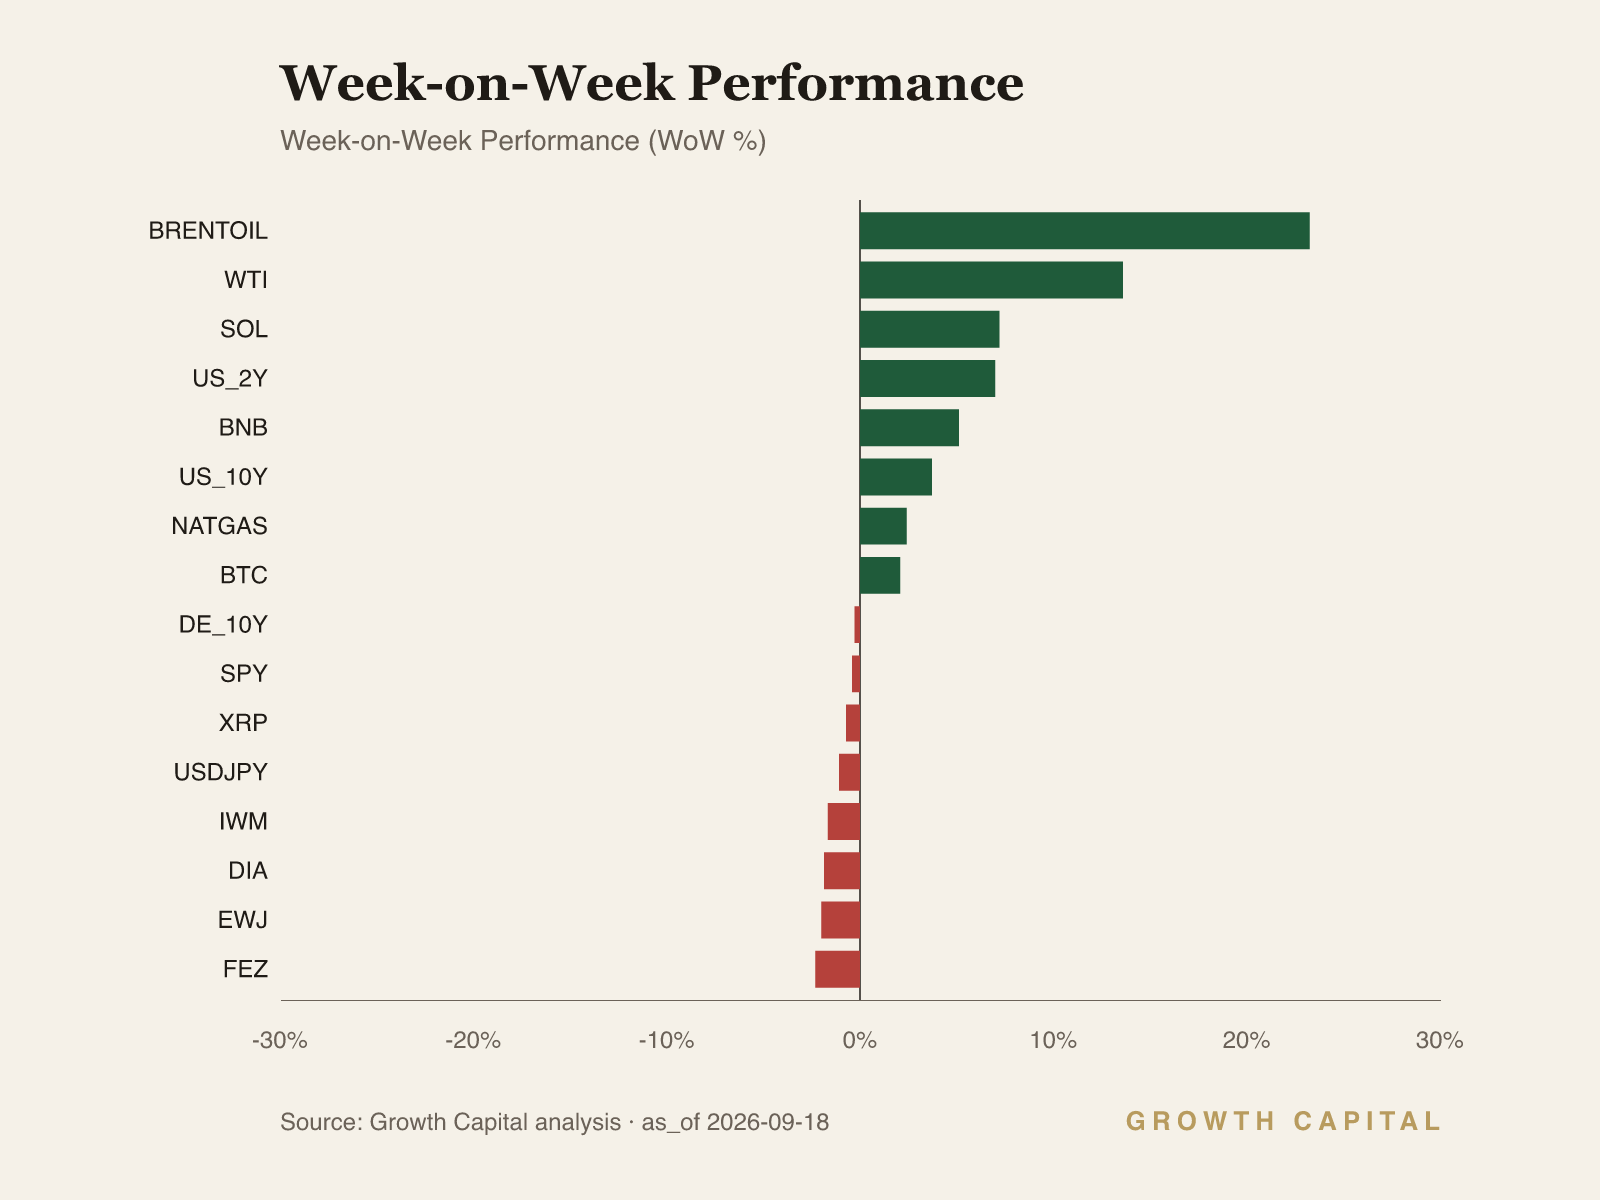
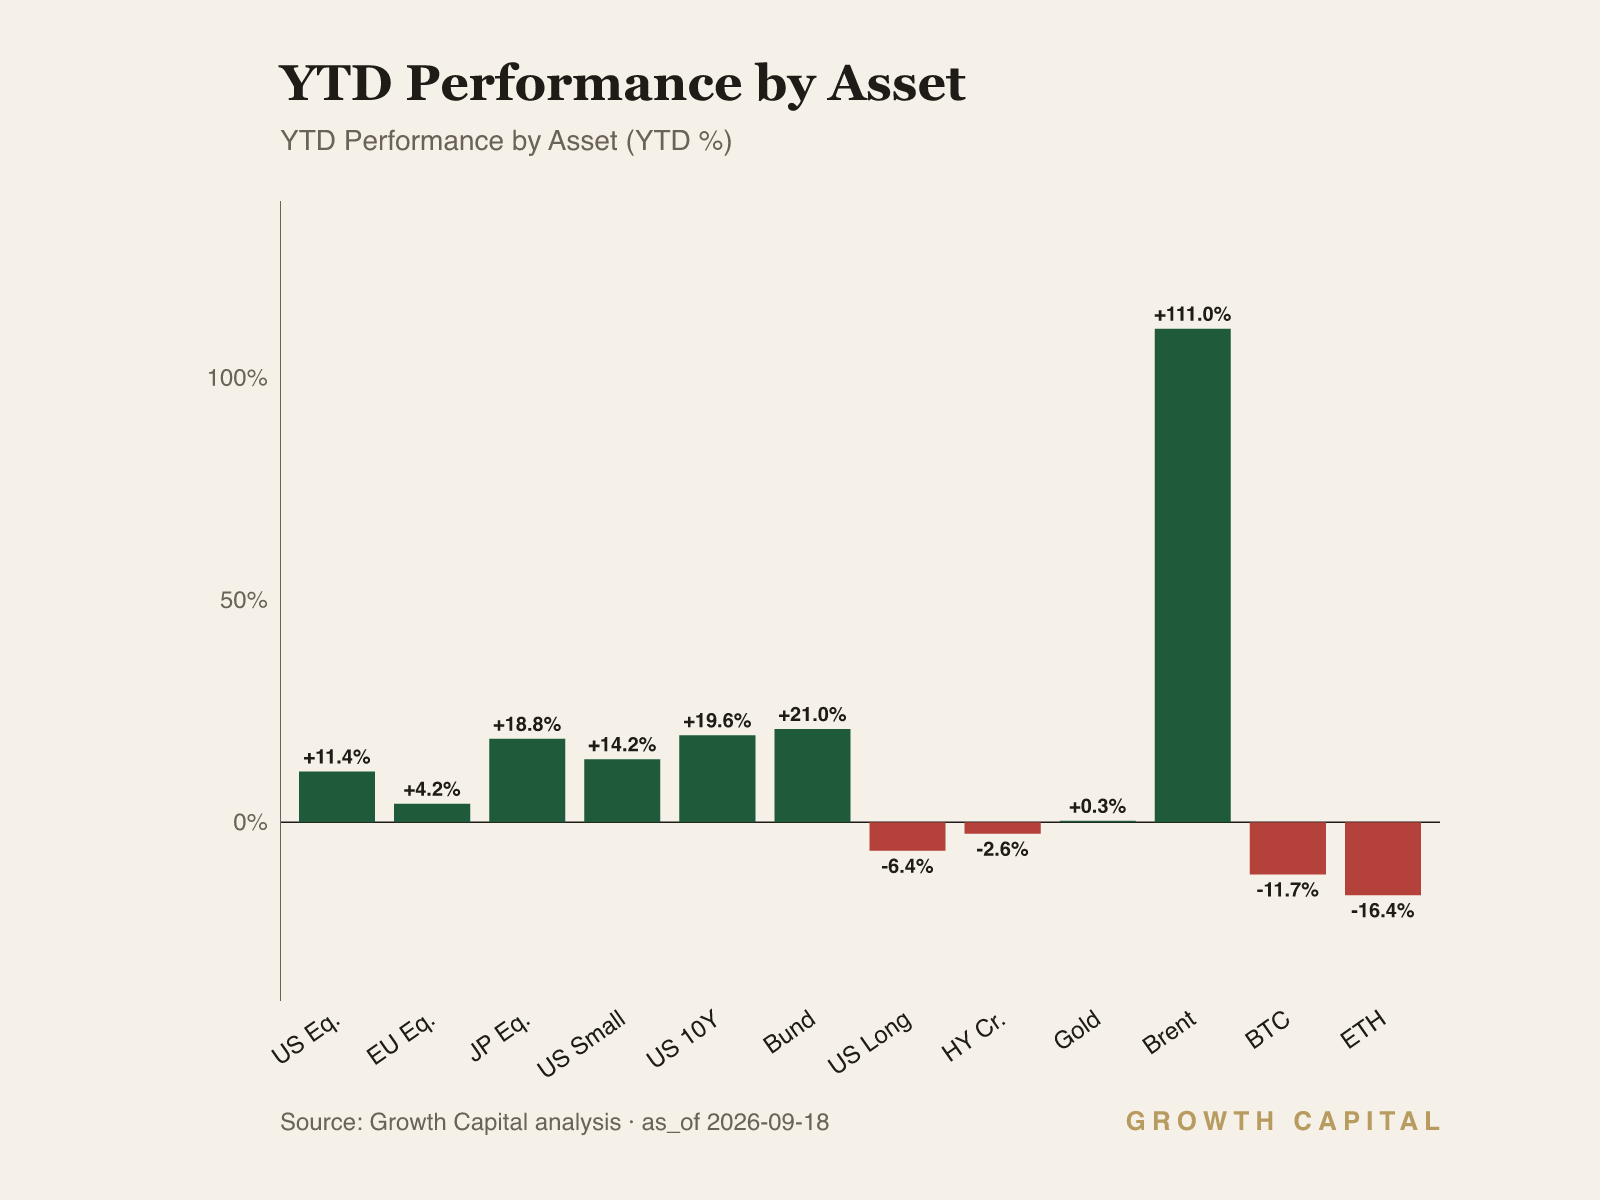
We label this week a hawkish resumption. The FOMC raised its funds target 25bp, taking the upper bound of the range to 4%, its first hike in three years, days after the ECB lifted its deposit rate 25bp to 2.5% and alongside a Bank of Japan move to a 1.25% overnight call-rate target. The bond market has taken the message at face value: the US 10Y printed 5.01%, +3.7% WoW and a 52-week high, and the 2Y reached 4.74%, +36.6% YTD and also at its high. Equities have not, with SPY off only -0.4% WoW at 761.10, still +11.4% YTD and just 2.2% below its 777.88 52-week high. Our thesis is that the discount-rate reset is real and the equity tape has not yet paid for it. Credit, quietly oversold across LQD, HYG and EMB, sides with the bond market rather than the index. We hold underweight long duration and reduced equity beta into Q4.
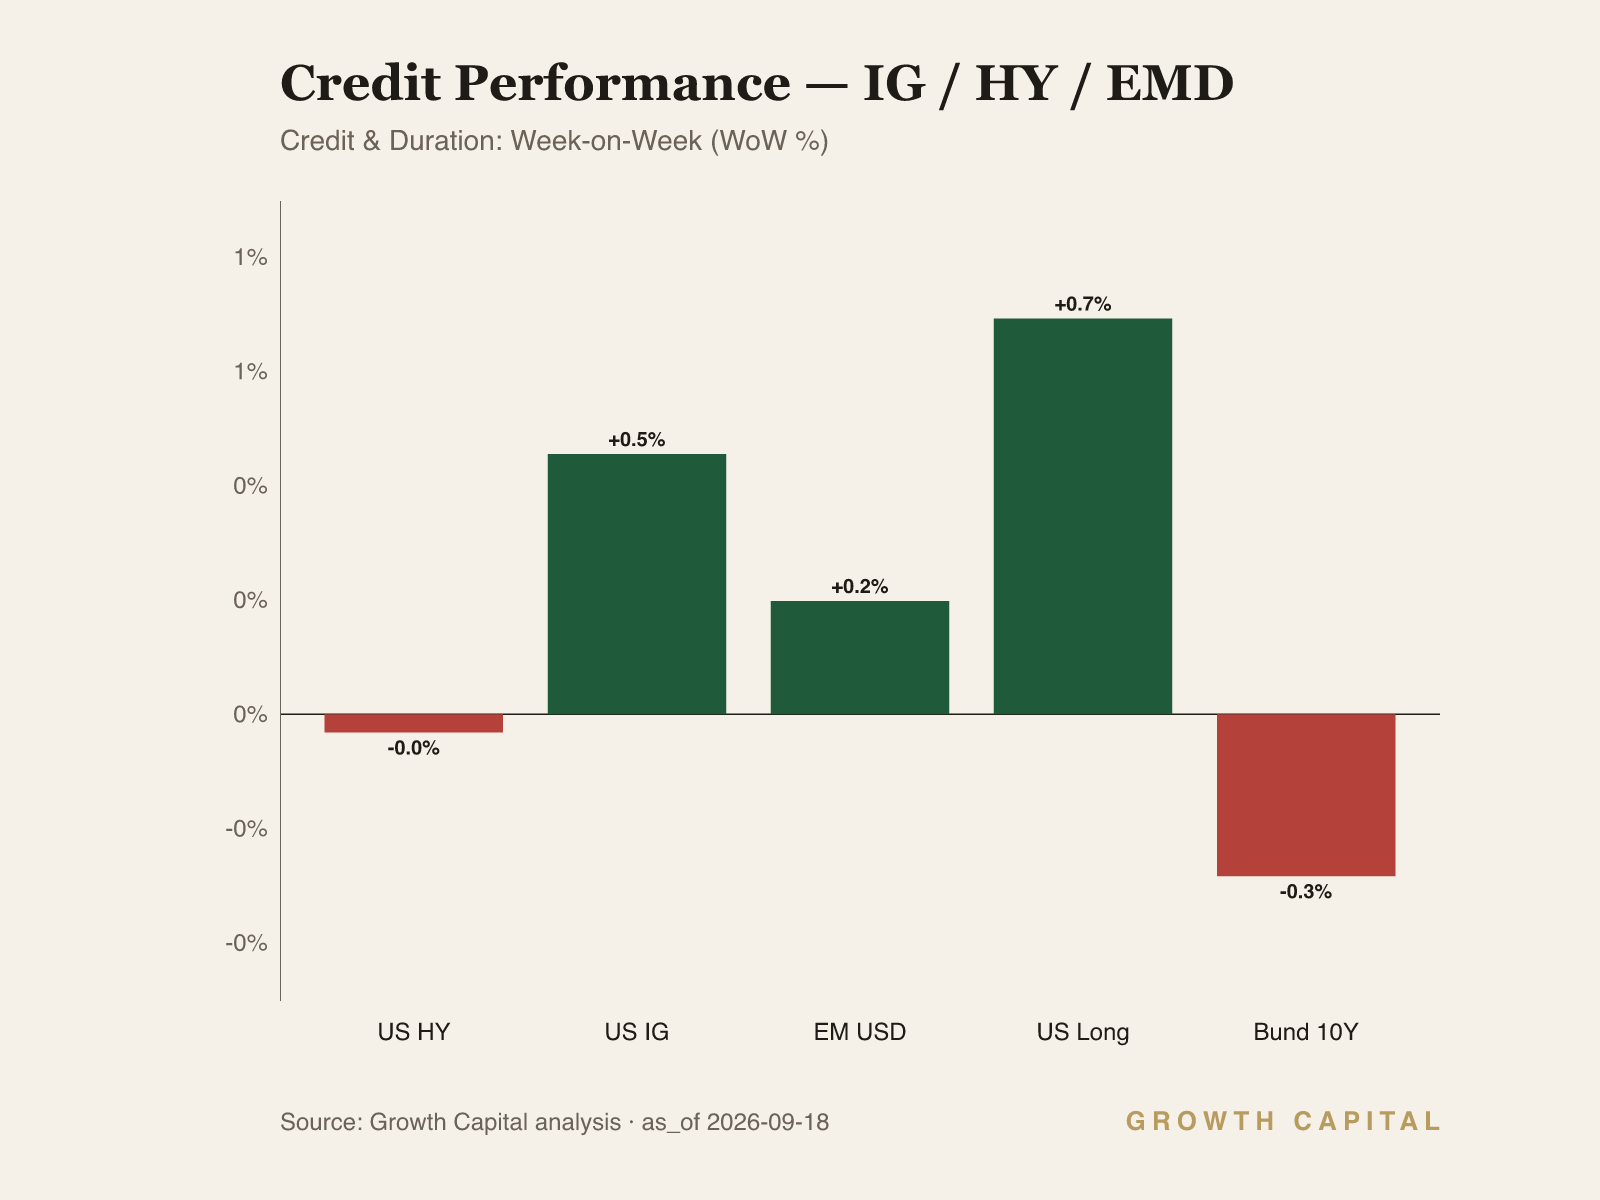
The primary chain runs through rates. The 10Y rose +3.7% WoW to 5.01% and the 2Y rose +7% WoW to 4.74%, both 52-week highs; in sympathy, TLT at 81.43 sits -6.4% YTD within a point of its 80.71 52-week low even after a +0.7% weekly bounce, LQD is -4.9% YTD and slightly oversold, and the dollar barely moved, DXY +0.1% WoW at 118.21. The transmission is rates to duration to multiples, one link at a time. The front end reprices first: with policy at a 4% upper bound and one further hike signalled, the 2Y's +36.6% YTD move raises the funding leg for every levered holder of long paper, and those holders shed their longest assets first. That selling pushes term premium out the curve, so the 10Y at 5.01% against the 2Y at 4.74% now leaves a +27bp gap, a re-steepening built on duration supply rather than growth optimism. The final link is the equity multiple: a 5.01% risk-free rate compresses the present value of long-dated cash flows, and the compression surfaced first in the rate-sensitive proxies, DIA -1.9% and IWM -1.7% WoW. We are underweight long duration on a three-to-six-month horizon and take the 4.74% front-end carry instead. The trade-off is explicit: we forgo convexity if growth cracks abruptly, and we accept reinvestment risk at the short end. A weekly 10Y close below 4.75% flips us to neutral; that level would say the market judges this range terminal, and that the mechanism has rotated from duration supply to growth fear.
Cross-asset, the equity and credit tapes disagree, and we side with credit. SPY fell -0.4% WoW to 761.10 while QQQ added +0.5% to 718.76; beneath them DIA lost -1.9%, IWM -1.7%, FEZ -2.3% and EWJ -2.0%, and HYG closed flat at 78.58, just 0.2% above its 78.38 52-week low, with EMB outright oversold at 93.53. The channel is positioning to liquidity to realised dispersion. Index resilience is crowding into the narrowest momentum cohort: QQQ's +17.2% YTD leadership dampens index-level volatility even as three of the four US proxies fall, and the exit door narrows as funding costs rise with the 2Y at 4.74%. When constrained investors concentrate in the same handful of long-duration growth names, the marginal seller in a drawdown is forced rather than discretionary, which is how low realised index volatility converts into gap risk. At the index level the equity tape contradicts our hawkish-resumption read; credit confirms it, and the gap quantifies the tension, SPY +11.4% YTD against LQD -4.9% YTD, a 16.3-point spread between claims on the same corporate cash flows. Credit has led equity at recent tightening turns, so we resolve in credit's favour: neutral SPY, underweight DIA and IWM, quality tilt across the sleeve into year-end. We accept the cost of lagging a further melt-up in the narrow leaders. A HYG close below 78.38 deepens the underweight and would say the funding channel is reaching cash flows, not just multiples; a 10Y back under 4.75% with high yield stable would argue the compression was rate-led, and we would re-add beta.
The second rail is FX, where the dollar's non-response is the tell. DXY sits at 118.21, +0.1% WoW and -1.2% YTD, slightly oversold despite the Fed hike; USDJPY fell -1.1% to 153.71 after the BoJ's move to 1.25%, while USDCHF rose +1.1% to 0.8159 and reads slightly overbought. A unilateral US hike should lift the dollar through the rate-differential channel, but it did not, because the Fed, ECB and BoJ tightened within the same fortnight and the differential barely moved. EURUSD at 1.1604, -0.2% WoW, confirms the stalemate. The coherence with our regime read matters: risk came off in equities without a dollar bid, which says the shock is global tightening rather than US-idiosyncratic stress, and argues against a dollar-funding squeeze. We are neutral EURUSD and carry a yen-strength bias while the BoJ normalises; a DXY push toward its 121.92 52-week high would force a reassessment for funding stress.
Our falsifiers are specific. On the downside, a HYG close below its 78.38 52-week low, or EMB through 92.95, converts an orderly repricing into credit-led risk-off; we would cut DIA and IWM to maximum underweight and add front-end Treasuries at 4.74%. On the upside, a weekly 10Y close below 4.75% alongside stable high yield would mark the terminal print, and we would neutralise the duration underweight and re-add equity beta toward SPY's 777.88 high. USDJPY through its 146.36 52-week low is the third trigger, because forced yen repatriation would pressure global duration beyond what the Fed path implies. One data caveat: our primary and crosscheck crude feeds diverged by more than 20% this week, so crude levels are excluded from the house view until the sources reconcile. The regime call stands until one of these levels prints.
Source: GrowthCapital analysis; market data per GC cross-asset snapshot as of 18 September 2026; policy decisions per Federal Reserve, ECB and Bank of Japan September 2026 releases.
Fixed Income
The front end is doing the tightening. The 2Y at 4.74%, +7% WoW and +36.6% YTD, sits at its 52-week high and now prices the new target range plus the additional hike the September statement signalled. The 10Y followed to 5.01%, +3.7% WoW and its own 52-week high, and the curve holds a +27bp gap (10Y 5.01% versus 2Y 4.74%), a re-steepening driven by duration supply rather than growth. The mechanism is funding cost: every levered holder of long paper faces a short-rate leg that has repriced +36.6% YTD, and the rational response is to shorten, which is why TLT at 81.43 sits -6.4% YTD within a point of its 80.71 52-week low even after a +0.7% weekly bounce. Credit carries the same rate beta: LQD at 104.80 is -4.9% YTD and slightly oversold, and HYG at 78.58 is -2.6% YTD, only 0.2% above its 52-week low, spread behaviour that is orderly but with no margin left. The Bund at 3.52%, -0.3% WoW, eased as European hike expectations moderated after the ECB's 25bp move, which leaves the US leg driving global term premium. Our positioning: underweight long duration, overweight front-end carry at 4.74%, neutral investment grade, underweight high yield. The trade-off is convexity forgone if growth breaks abruptly. A weekly 10Y close below 4.75% neutralises the duration call; a HYG break of 78.38 converts the high-yield underweight into a broader risk reduction across the book.
Equities
Index resilience is narrower than it looks. SPY fell -0.4% WoW to 761.10 and holds +11.4% YTD, but the internals split: QQQ gained +0.5% to 718.76 (+17.2% YTD) while DIA lost -1.9%, IWM -1.7%, FEZ -2.3% and EWJ -2.0%. Three of the four US proxies fell in a week the 10Y printed 5.01%; the one that rose is the longest-duration cohort in the market, which is a positioning statement, not a valuation one. The mechanism: constrained investors crowd the narrow momentum leadership because it has carried the year, and that crowding suppresses index volatility while raising gap risk, since the marginal seller in a drawdown is forced rather than discretionary. Small caps feel the funding channel first, with the 2Y at 4.74% resetting the cost of the floating-rate liabilities that sit disproportionately on Russell 2000 balance sheets, hence IWM's -1.7% week despite a +14.2% YTD. Europe and Japan gave back more, FEZ -2.3% and EWJ -2.0%, though EWJ's +18.8% YTD still leads developed markets after the BoJ's move to 1.25% validated the reflation story its multiple had been pricing. We are neutral SPY and QQQ, underweight DIA and IWM, neutral FEZ and EWJ, with a quality tilt across the sleeve. The falsifier: a weekly 10Y close below 4.75% with breadth broadening, DIA and IWM outperforming QQQ, moves us back to benchmark beta; SPY pushing toward its 777.88 high on current breadth would not.
Digital Assets
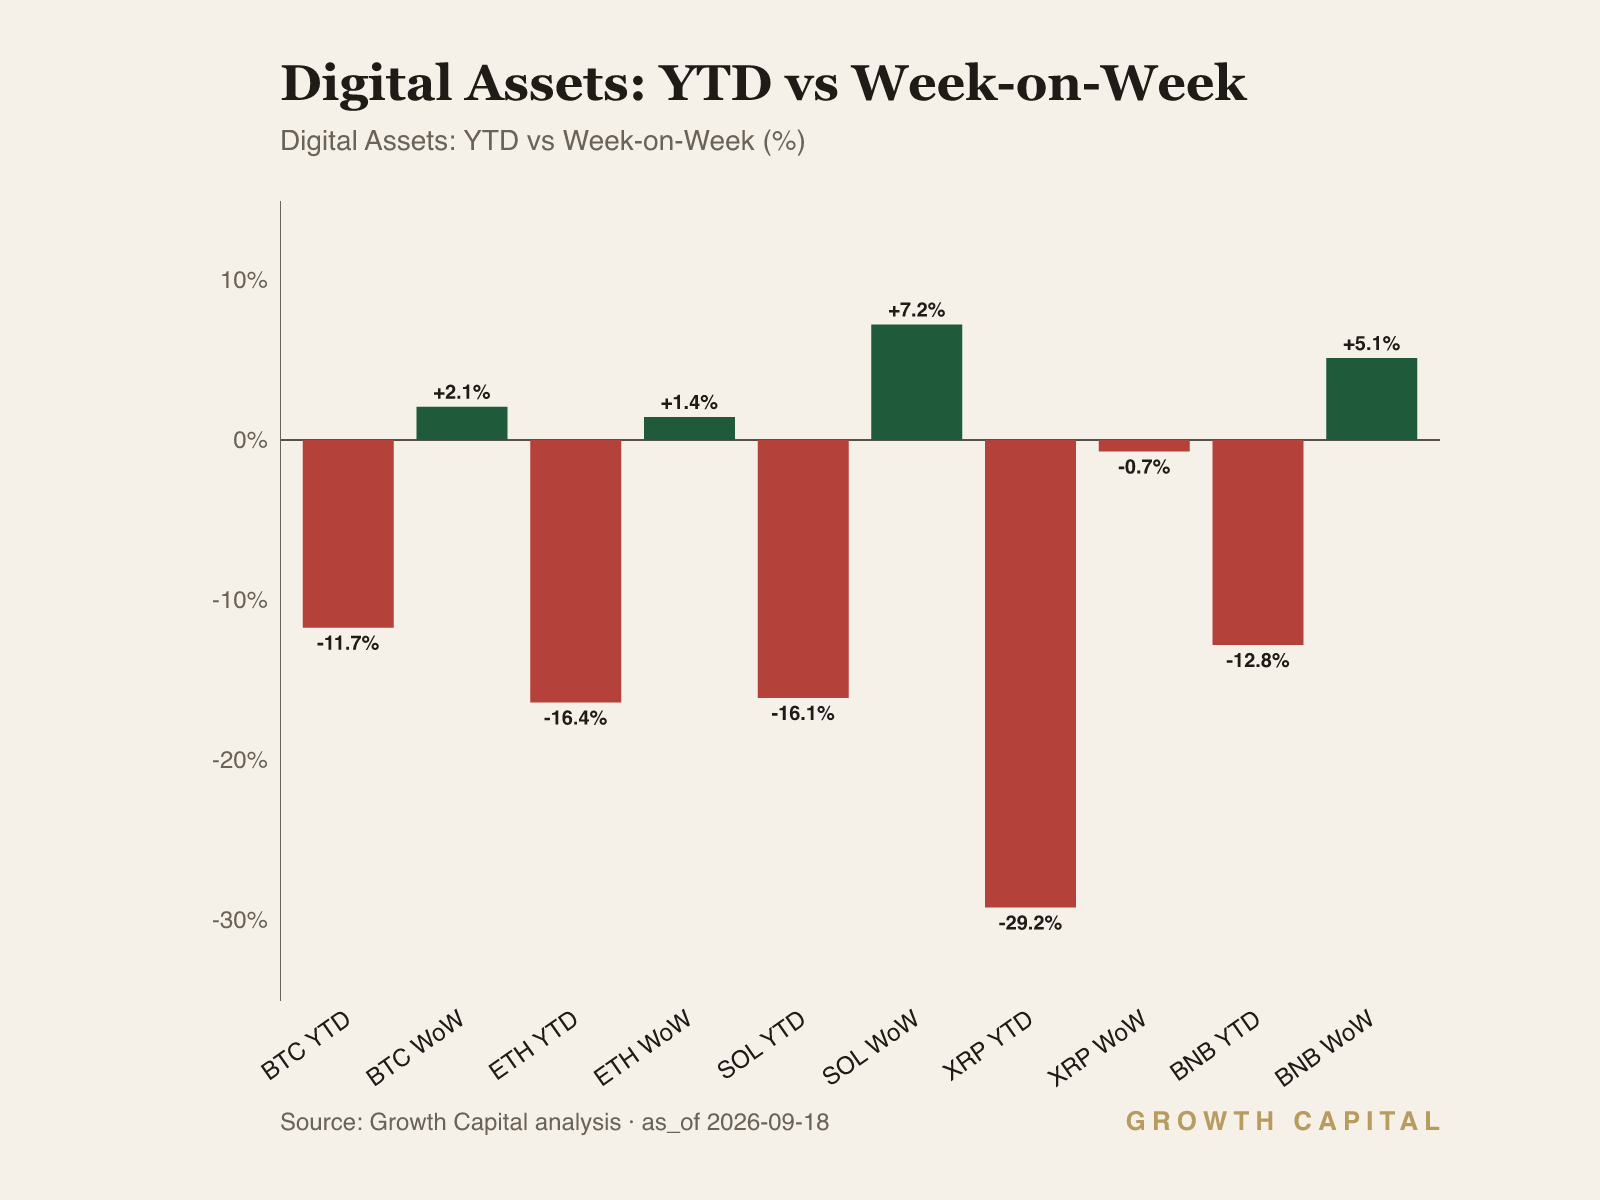
Crypto firmed into a hawkish week, which is itself information. BTC rose +2.1% WoW to $78,382, dominance is 55.94%, and total market capitalisation stands at $2.80T, +2.66% over 24 hours on $146.8B of volume. ETH added +1.4% to $2,510.94 and SOL led the majors at +7.2% to $106.41, both slightly overbought; the YTD ledger is still negative across the board, BTC -11.7%, ETH -16.4%, SOL -16.1%. The week's setback was legislative: the Clarity Act failed a key Senate procedural vote, removing the near-term regulatory-framework catalyst, and the tape absorbed it without breaking the uptrend, which argues the marginal buyer is positioning-driven rather than headline-driven. On-chain, the derivatives lean among Nansen-labelled smart traders is long-heavy across BTC, ETH and SOL, while spot cohorts distributed into strength in SOL specifically; that spot-versus-perps split is the sleeve's main fragility. With the 2Y at 4.74%, the opportunity cost of a non-yielding volatile asset is at cycle highs, so we require spot confirmation before adding. We are neutral BTC and ETH, neutral SOL with a tactical fade bias given the distribution, and we keep the sleeve small relative to strategic targets. BTC holding its uptrend with dominance at 55.94% and continued exchange outflows would upgrade the stance; a failure back through the YTD downtrend, or liquidation cascades in the overbought alts, would cut the sleeve further.
GC Views
| Asset | View | Rationale |
|---|---|---|
| US_10Y | UW | 5.01% is a 52w high with one more hike signalled; underweight duration until a weekly close below 4.75%. |
| US_2Y | OW | 4.74% front-end carry near terminal policy; the best-paid patience on the curve. |
| DE_10Y | N | 3.52%, -0.3% WoW as ECB expectations moderate; the US leg drives global term premium. |
| TLT | UW | -6.4% YTD within a point of the 80.71 low; convexity not yet worth the negative carry. |
| LQD | N | -4.9% YTD and sl. oversold; rate beta, not spread stress, is doing the damage. |
| HYG | UW | 78.58 sits 0.2% above the 52w low; a close below 78.38 confirms credit-led risk-off. |
| SPY | N | +11.4% YTD against a 5.01% risk-free; multiple risk caps upside and breadth is narrowing. |
| QQQ | N | +17.2% YTD on the narrowest leadership; crowding adds gap risk faster than return. |
| DIA | UW | -1.9% WoW; rate-sensitive cyclicals absorb the duration repricing first. |
| BTC | N | +2.1% WoW to $78,382 with a long-heavy smart-trader lean; -11.7% YTD caps conviction. |
| GLD | N | +0.3% YTD; 5.01% nominals cap upside but we hold it as inflation-regime insurance. |
| EURUSD | N | 1.1604 with Fed and ECB hiking in the same fortnight; differentials static, range trade. |
On-Chain Pulse
The aggregate on-chain pattern this week is long-heavy derivatives positioning set against mixed spot flows. Nansen-labelled smart traders and funds lean long across BTC, ETH, SOL and BNB perps, while spot cohorts distributed WBTC and SOL and exchange balances fell materially for ETH and BNB. XRP is the outlier, showing perp buy pressure with no meaningful smart-trader spot participation.
Bitcoin's picture is constructive but not clean. Labelled smart-trader and fund derivatives positioning is long-heavy, though fund-only 7-day netflow data was unavailable this week, so we do not quote cohort dollar sizing on the perp leg. On spot, Ethereum-chain WBTC registered a -$115.4k 7-day net flow across 11 smart-trader and fund addresses, flat over the past 24 hours, modest distribution relative to the asset's scale. The heavier flows sat in holder segments: Top-PnL wallets moved $33.5M out and public-figure wallets $7.8M out over the week, against a $7.6M net outflow from exchange wallets that reduced immediately exchange-held supply, with the Binance 14 wallet adding to its WBTC balance. That is the spot-versus-perps divergence to respect: perps lean long while the best-performing spot wallets trim. With BTC +2.1% WoW to $78,382 and dominance at 55.94%, we stay neutral and would add only on spot cohorts turning net buyers.
Ethereum carries the same long-heavy derivatives lean among labelled smart traders, and per-cohort dollar sizing on the perp book was likewise not published this week. The distinguishing signal is supply-side: exchange balances fell materially over the seven days, which under the flow methodology reduces immediately sellable inventory. Labelled spot flow was otherwise quiet, so the divergence is a constructive perp lean against a passive spot book rather than active accumulation. Price confirms the lean at the margin, +1.4% WoW to $2,510.94, though the token reads slightly overbought and remains -16.4% YTD. We hold ETH at neutral and would upgrade on a second consecutive week of exchange drawdown with labelled spot cohorts turning net buyers.
Solana shows the sleeve's cleanest divergence. The derivatives lean among labelled smart traders is long-heavy, consistent with the majors, again without published cohort dollar sizing this week. Against it, Top-PnL spot cohorts distributed on Solana-chain SOL, selling the very rally that took the token +7.2% WoW to $106.41. When the best historical performers sell spot into a perp-led advance, the advance is renting its buyers, and SOL's slightly overbought reading on a -16.1% YTD base sharpens the asymmetry. Open-interest-led moves without spot sponsorship tend to retrace toward the spot bid. We rate SOL neutral with a tactical fade bias and would not chase strength at these levels.
XRP is the most mixed profile in the intel set. Perp flow shows positive buy pressure, but there is no meaningful smart-trader spot flow on BNB Chain to accompany it, leaving the derivatives bid unsponsored. The price tape agrees with the caution: -0.7% WoW to $1.3291 and -29.2% YTD, the worst of the majors by a wide margin. A perp-led bid without spot participation is the most fragile configuration in this week's data because it depends entirely on positioning persistence. We hold XRP at the bottom of the digital sleeve and require labelled spot accumulation before revisiting.
BNB pairs the long-heavy smart-trader derivatives lean with the week's second material exchange-balance drawdown, matching the ETH pattern. Falling exchange balances reduce immediately sellable supply, the supply-side complement to the perp-side demand signal. Price responded, +5.1% WoW to $752.65, though the token is slightly overbought and remains -12.8% YTD, so the move recovers drawdown rather than extends a trend. Cohort dollar sizing on the perp book was not published for BNB either, so we weight the balance signal over the positioning one. We hold BNB at benchmark within the sleeve; a third week of exchange outflows with price holding its gains would justify a modest add.
What We're Watching
Four triggers govern the stance. A weekly 10Y close below 4.75% neutralises our duration underweight and re-adds equity beta; a print above the 5.01% high extends both underweights. HYG below its 52-week low of 78.38, or EMB through 92.95, converts orderly repricing into credit-led risk-off and takes DIA and IWM to maximum underweight. USDJPY through 146.36 signals repatriation pressure on global duration beyond what the Fed path implies. In digital assets, BTC losing its uptrend with dominance below 55.94% cuts the sleeve, while sustained exchange outflows with spot-led strength upgrade it. Crude feeds must also reconcile, primary versus crosscheck divergence exceeded 20% this week, before energy re-enters the house view.
This Week in Charts